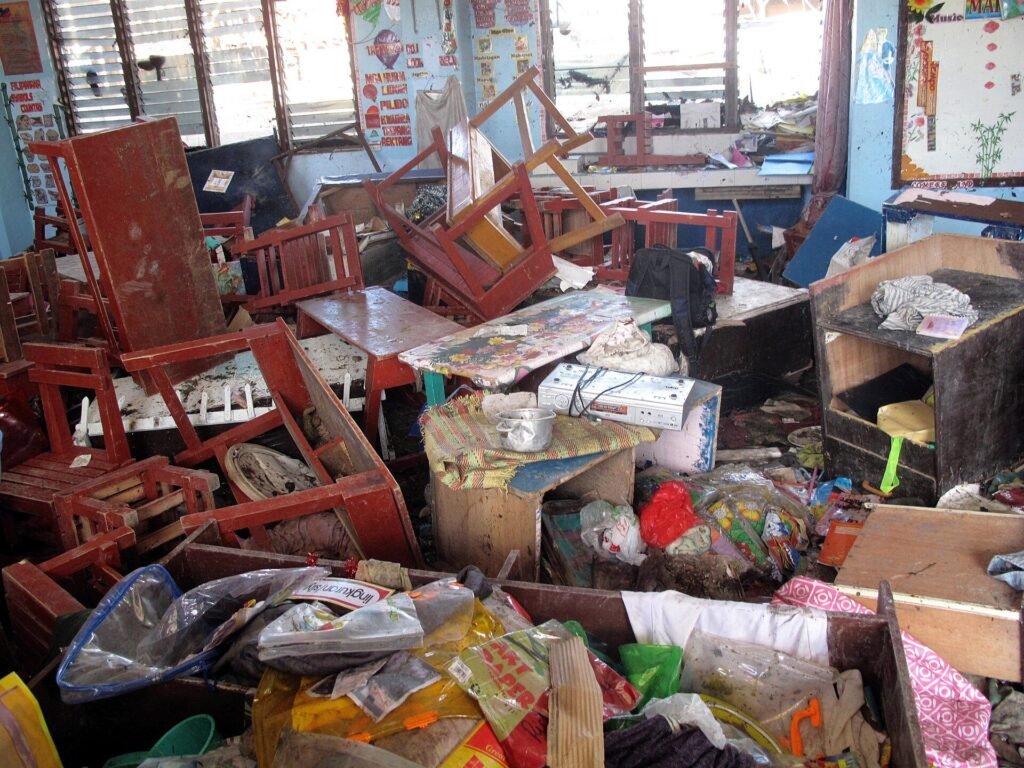
The Pag-IBIG Calamity Loan is an emergency cash loan for Pag-IBIG Fund members. They can take it when authorities declare a state of calamity where they live, or in some cases where they work. It lends against your own savings at a fixed rate of 5.95 percent a year, with a three-month grace period. You must apply within 90 days from the declaration. The details below come from the Calamity Loan Application Form (HQP-SLF-066), version 11 dated May 2025.
When the Pag-IBIG Calamity Loan becomes available
The Pag-IBIG Calamity Loan is not open all the time. It opens only after a state of calamity declaration, for example after a typhoon, flood, or earthquake. The national government or local government units, through their sanggunian, make these declarations. After a major disaster, Pag-IBIG usually announces the covered areas. It often pairs this with other relief, such as housing loan payment moratoriums.
The 90-day clock starts on the date of the declaration. If you miss it, you will need to wait for another declaration or use the Multi-Purpose Loan instead.
Who qualifies for a Pag-IBIG Calamity Loan
According to the current form, a member qualifies if he or she:
- has made at least 12 monthly membership savings;
- is an active member at the time of application;
- has no defaulted Multi-Purpose Loan, Calamity Loan, or Health and Education Loan (HELPs);
- lives in an area declared calamity-stricken, or works in a place declared under a state of calamity, subject to management approval; and
- has sufficient proof of income.
A member with fewer than 12 monthly savings may still qualify if total savings already equal 12 months at his or her contribution rate. A member who withdrew savings at maturity or through optional withdrawal can qualify again after accumulating 12 more monthly savings.
How much a Pag-IBIG Calamity Loan can give you
Pag-IBIG approves the lowest of three amounts:
- Desired loan amount, the figure you request.
- Loan entitlement, which is 90 percent of your Total Accumulated Value (TAV). If you already have an MPL, Calamity Loan, or HELPs balance, the entitlement is 90 percent of TAV minus that balance.
- Capacity to pay, meaning the amortization must not push your net take-home pay below the minimum under the General Appropriations Act or company policy.
Your TAV includes your own savings, your employer’s contributions, and dividends. For instance, a member with a TAV of ₱30,000 and no existing short-term loan has an entitlement of ₱27,000. In no case can total short-term loans exceed 90 percent of TAV.
Pag-IBIG Calamity Loan interest, term, and grace period
The Pag-IBIG Calamity Loan carries an interest rate of 5.95 percent a year. Interest also accrues during the grace period, and Pag-IBIG spreads it over the loan term. You choose a term of one, two, or three years when you apply; if you do not choose, the default is two years. There is a three-month grace period, so the first payment falls due on or before the 15th day of the fourth month after release.
Employees normally pay through salary deduction. Self-employed members, OFWs, and other individual payors pay over the counter or through other channels approved by the Fund. You can also pay off the loan early without waiting for maturity.
Documents for a Pag-IBIG Calamity Loan
Prepare the following:
- the accomplished Calamity Loan Application Form, one copy;
- a valid ID, with a photocopy if filing at a branch;
- proof of income, such as recent payslips for employees or other income documents for self-employed members;
- details of your disbursement account, such as a Loyalty Card Plus or a bank account accepted by Pag-IBIG.
Employed members also need the employer’s certification portion of the form completed, which confirms employment and net pay. According to the form, processing starts only once the documents are complete. If the disaster damaged or destroyed your ID, see our valid government IDs guide for alternatives.
How to apply for a Pag-IBIG Calamity Loan
The form says to get the application form from any Pag-IBIG branch or download it from the Pag-IBIG website, fill out one copy, and submit it with the required documents to any branch. In practice, Pag-IBIG also accepts short-term loan applications through Virtual Pag-IBIG and, for employees, sometimes through the employer. After a large disaster, Pag-IBIG may also set up help desks or extend branch hours in affected areas.
When filing online, keep the reference number and track the status in your account. When filing at a branch, ask for a receiving copy.
How the money is released
Pag-IBIG releases loan proceeds by crediting your disbursement card or Loyalty Card Plus, crediting your bank account through Landbank’s payroll credit validation system, or by check. Pag-IBIG may cancel a check left unclaimed for 30 calendar days after notice, so watch your email and phone for release notices.
Penalties and default on a Pag-IBIG Calamity Loan
Late payments carry a penalty of 1/20 of 1 percent of the unpaid amount for every day of delay. If an employer deducted the payment but failed to remit it, Pag-IBIG charges the penalty to the employer once you show proof.
You are in default if you miss three consecutive amortizations, miss three consecutive monthly savings, make a willful misrepresentation, or violate Pag-IBIG’s loan rules. In default, the whole balance becomes due, and Pag-IBIG offsets it against your TAV without further demand. As a result, your savings shrink, and a new loan may be delayed by up to a year depending on how many payments you made before default.
A worked example
Consider an employee in a town declared under a state of calamity after a typhoon. She has 40 monthly savings and a TAV of ₱24,000, and she has an existing MPL balance of ₱6,000. Her entitlement is 90 percent of ₱24,000, which is ₱21,600, minus the ₱6,000 MPL balance, leaving ₱15,600. She asks for ₱15,000, and her payslip shows enough take-home pay to cover the amortization, so the approved amount is ₱15,000.
She chooses a two-year term. Since there is a three-month grace period, her first salary deduction happens in the fourth month after release. Meanwhile, interest already runs during those three months, and Pag-IBIG spreads it over the loan’s amortizations. If she later gets a bonus, she can pay the balance in full before maturity.
Calamity Loan alongside the MPL
The Calamity Loan, the Multi-Purpose Loan, and HELPs are separate products. You can take a Calamity Loan even if you have an MPL, and vice versa. However, the combined balance cannot exceed 90 percent of TAV, so an existing MPL reduces what you can borrow. Our Pag-IBIG Multi-Purpose Loan guide explains the MPL’s own rules.
If another calamity hits the same area, you can renew the Pag-IBIG Calamity Loan at any time. Pag-IBIG deducts the outstanding balance, with any interest and penalties, from the new loan’s proceeds.
Early offsetting for hardship
A borrower may ask Pag-IBIG to offset the outstanding balance against TAV immediately for justifiable reasons listed on the form: total disability or insanity, separation from service due to health, death of an immediate family member, unemployment due to layoff or company closure, critical illness of the borrower or an immediate family member (cancer, organ failure, heart-related illness, stroke, or neuromuscular illness), repatriation of an OFW borrower, and other grounds approved by the Board.
Tips for filing after a disaster
Disasters create queues. To avoid wasted trips, check first whether your employer is collecting applications in bulk, since many HR offices do this after a major storm. If you are filing yourself, use Virtual Pag-IBIG when the internet is back, and save screenshots of each step. Bring photocopies of your ID to the branch, since photocopy shops near government offices may be closed or crowded after a calamity. For more on preparing documents, see our government ID and document prep checklist.
Members with more than one employer
A member with several employers can have only one outstanding Pag-IBIG Calamity Loan at a time. At application, you choose which employer will deduct and remit the amortizations. If your address or contact details changed because of the disaster, you can update them directly on the loan form without a separate change-of-information form.
Other help after a disaster
The Pag-IBIG Calamity Loan is one source of help, not the only one. SSS also opens a calamity loan program for members in declared areas, with its own rules. The DSWD’s Assistance to Individuals in Crisis Situations can help with food, medical, or burial needs; see the DSWD page on AICS. Housing loan borrowers should also ask Pag-IBIG about any payment moratorium announced for the area. For preparing before the next storm, our typhoon season guide has a checklist.
Quick checklist
- Confirm your city or municipality is under a declared state of calamity.
- Check that you have 12 monthly savings and no defaulted short-term loans.
- Prepare your ID, proof of income, and disbursement account details.
- Apply within 90 days of the declaration.
- Choose a one-, two-, or three-year term, and note when the first payment is due.
Last checked against the Pag-IBIG Fund Calamity Loan Application Form (HQP-SLF-066, V11, May 2025), available from the Pag-IBIG Fund website, and RA 9679 on Lawphil on October 2026. Pag-IBIG can revise loan terms, so the version of the form you submit governs your loan.